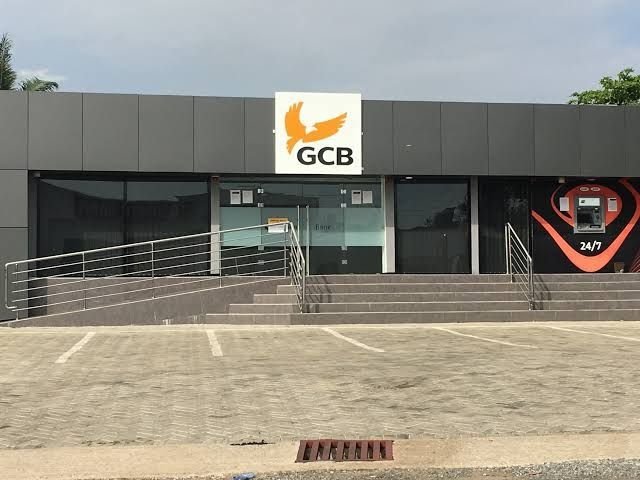
GCB Bank PLC’s profit after tax rose 39% to GH¢629.11 million in the third quarter of 2026, compared with GH¢451.07 million during the same period last year.
For the nine months to September, the bank’s profit increased 44% to GH¢1.86 billion, from GH¢1.29 billion in 2025. Including its subsidiaries, GCB Bank’s group profit reached GH¢1.87 billion.
The figures were contained in unaudited statements released through the Ghana Stock Exchange on October 26. The third-quarter result represents the difference between the nine-month total and the GH¢1.23 billion recorded in the first half.
GCB Bank’s performance contrasts with the wider sector, where banks’ combined profit after tax fell 5.7% to GH¢9.2 billion in the eight months to August, according to the Bank of Ghana’s October Banking Sector Development Report. The report attributed the decline partly to lower lending rates reducing interest income.
Interest income at GCB Bank increased 1.3% to GH¢4.39 billion. Within that figure, interest earned from loans rose 40.5% to GH¢2.51 billion, while income from investment securities, mainly government paper, declined 24.6% to GH¢1.71 billion as yields fell.
The bank’s interest expense dropped 31.9% to GH¢816 million, lifting net interest income by 14% to GH¢3.57 billion. The Ghana Reference Rate, used by banks to price loans, fell to 10.01% for November.
Fee and commission income grew 68% to GH¢1.32 billion. Processing and facility fees more than doubled, rising from GH¢171.5 million to GH¢408.4 million.
Net trading income increased 72% to GH¢1.01 billion, including GH¢625.9 million from fixed-income trading and GH¢380.8 million from foreign exchange. Operating income rose 32% to GH¢5.70 billion, while taxes and levies totalled GH¢1.01 billion, equivalent to about 35% of pre-tax profit of GH¢2.87 billion.
Net loans to customers reached GH¢25.23 billion at the end of September, an 83% rise from GH¢13.77 billion a year earlier. Gross loans increased 66% to GH¢26.33 billion, while the credit impairment allowance fell from GH¢1.77 billion to GH¢907.4 million.
Customer deposits grew 34% to GH¢50.40 billion, with about 93% held in current and savings accounts. Loans represented about half of deposits, compared with roughly 37% a year earlier.
Total assets rose almost 36% to GH¢67.62 billion, ahead of the 20.5% growth recorded across Ghana’s banking sector in the year to August.
GCB Bank’s non-performing loan ratio improved to 4.8% from 10.8% in September 2025, although it was slightly higher than the 4.7% recorded at the end of June. Impairment charges rose 51% to GH¢260.1 million as lending expanded.
The capital adequacy ratio fell to 14.6%, from 16.2% a year earlier and 15.9% in June. The liquid ratio declined from 73.4% to 64.3%.
The accounts also reported GH¢492,000 in “other regulatory sanctions”, compared with none the previous year, without specifying their nature.
Third-quarter operating expenses were GH¢938 million against income of GH¢1.97 billion, producing a cost-to-income ratio of 47.7%. For the nine months, the ratio improved to 45.1% from 49.2%.
Personnel costs rose 22% to GH¢1.45 billion, including GH¢329.5 million in performance awards, up from GH¢237.4 million. GCB Bank paid GH¢265 million in dividends, while earnings per share increased to GH¢9.38 from GH¢6.51.
Board chairman Prof. Joshua Alabi and managing director Farihan Alhassan signed the statements. Fitch Ratings said last month that Ghana’s banking sector had healthy profitability metrics.